HMO vs PPO Medicare Advantage Plans in Florida: What’s the Difference?
Choosing a Medicare Advantage plan is not only about finding a plan with a low premium. The way you access doctors, specialists, hospitals, prescriptions, and other covered services can also
Choosing a Medicare Advantage plan is not only about finding a plan with a low premium. The way you access doctors, specialists, hospitals, prescriptions, and other covered services can also affect your healthcare experience and out-of-pocket costs. For Florida residents comparing Medicare Advantage plans, one of the most important differences to understand is HMO vs PPO Medicare Advantage Florida.
HMO and PPO are two common types of Medicare Advantage plans. Both are offered by private insurance companies approved by Medicare, and both cover Medicare Part A and Part B services. However, they can differ in provider networks, referrals, out-of-network coverage, and how you access care.
The right comparison starts with how each plan works rather than simply looking at the monthly premium. This guide explains the difference between HMO and PPO Medicare Advantage plans in Florida, including provider networks, specialist referrals, costs, prescription drug coverage, and the practical questions to ask before enrolling.
These are general plan-type differences, not guarantees for every plan. Medicare notes that HMO-POS plans can allow certain out-of-network services, while individual HMO and PPO plans can have their own network and cost-sharing rules.
What Is a Medicare Advantage HMO Plan?
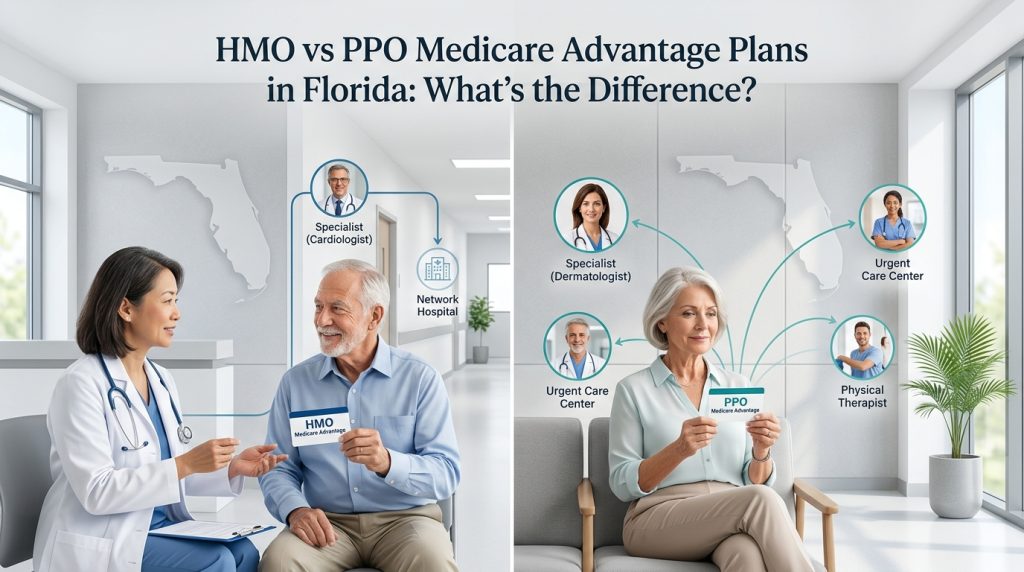
A Medicare Advantage HMO, or Health Maintenance Organization, is a Medicare Part C plan that generally requires you to receive covered care from doctors, hospitals, and other healthcare providers within the plan's network. There are exceptions, including emergency care, out-of-area urgent care, and certain temporary dialysis services. Most HMO Medicare Advantage plans also require members to choose a primary care doctor. Your primary care doctor can help coordinate your routine healthcare and, in most cases, provide referrals when you need to see a specialist. Some services may not require a referral, so the specific plan rules should always be checked before receiving care. For someone who regularly uses doctors and hospitals in the same local area, an HMO structure can make healthcare easier to coordinate. The important point is that the provider network matters. Before enrolling, check whether your preferred primary care doctor, specialists, hospitals, and other frequently used providers participate in the specific plan.What Is a Medicare Advantage PPO Plan?
A Medicare Advantage PPO, or Preferred Provider Organization, also has a network of doctors, hospitals, and other healthcare providers. However, PPO plans generally give members more flexibility to receive covered services from providers outside the plan's network. Using out-of-network providers usually means paying a higher share of the cost. Unlike most HMO plans, Medicare Advantage PPO plans do not require you to choose a primary care doctor, and you generally do not need a referral to see a specialist. This can be useful for people who want more direct access to specialists or who regularly receive care from providers in different locations. However, having out-of-network coverage does not mean that every provider or service will automatically be covered. You should confirm the plan's rules before receiving non-emergency care outside the network.HMO vs PPO Medicare Advantage Florida: Key Differences
The main difference between HMO and PPO Medicare Advantage plans is how they handle provider networks and access to care. HMOs generally place more emphasis on using an in-network care system, while PPOs generally provide more flexibility to use out-of-network providers at a higher cost.| Feature | HMO Medicare Advantage | PPO Medicare Advantage |
| Provider network | Generally must use in-network providers for covered care | Can generally use in-network or out-of-network providers |
| Primary care doctor | Usually required | Generally not required |
| Specialist referral | Usually required | Generally not required |
| Out-of-network care | Generally limited, except for certain situations | Generally covered at a higher cost |
| Prescription coverage | Usually available through the plan | Usually available through the plan |
| Provider flexibility | More limited | Generally greater |
| Plan-specific costs | Depend on the plan | Depend on the plan |
HMO vs PPO: How Provider Networks Work
Provider networks are one of the most important things to understand when comparing Medicare Advantage plans. An in-network provider has a contract with the Medicare Advantage plan. Using these providers generally means you receive the cost-sharing listed by your plan. An out-of-network provider is outside that contracted network, and the plan may charge you more or, depending on the plan type and service, may not cover the care at all. For HMO Medicare Advantage plans, staying within the network is generally important for non-emergency care. Medicare states that HMO members generally must receive care from providers and facilities in the plan's network, with specific exceptions. PPO Medicare Advantage plans provide more flexibility. You can generally use out-of-network providers for covered services, but your share of the cost is usually higher. Medicare recommends checking with the plan before using an out-of-network provider to confirm that the service is covered and medically necessary. This makes checking the provider network an important step before enrolling. If you already have a primary care doctor or specialist you want to continue seeing, verify that provider's participation in the exact plan rather than assuming that the provider accepts all plans from the same insurance company.HMO vs PPO: Primary Care Doctors and Specialist Referrals
Another important difference between HMO and PPO Medicare Advantage plans is how you access specialist care. Most HMO plans require you to select a primary care doctor and generally require a referral before seeing a specialist. This means your primary care doctor often plays a central role in coordinating your healthcare. PPO plans generally do not require you to select a primary care doctor or obtain a referral before seeing a specialist. You can usually contact a specialist directly, subject to the plan's coverage and network rules. For example, imagine a Florida resident who regularly sees a cardiologist. With an HMO, the person may need to first work through their primary care doctor if the plan requires a referral. With a PPO, the member can generally schedule covered specialist care without that referral requirement. The specific plan still matters. Certain services may require prior authorization, and plan rules can change from one Medicare Advantage plan to another. Medicare advises members to check their plan's requirements before receiving services.HMO vs PPO Medicare Advantage Costs
Cost is another major part of the HMO vs PPO comparison, but monthly premiums alone do not tell you how much a plan will cost overall. Medicare Advantage plans can have a monthly premium in addition to the Part B premium, although the amount varies by plan. You should also look at deductibles, copayments, coinsurance, prescription drug costs, and the plan's annual maximum out-of-pocket limit when comparing coverage. HMO plans may have lower costs for certain services when you stay within the network, but that does not mean every HMO is less expensive than every PPO. Likewise, a PPO may have a higher premium or higher cost-sharing for some services, but the additional flexibility may be valuable to someone who regularly uses out-of-network providers. A better approach is to estimate your likely yearly healthcare use. Consider how often you visit doctors, whether you see specialists, what prescriptions you take, which hospitals you use, and whether you expect to receive care outside your local area.Look Beyond the Monthly Premium
When comparing Medicare Advantage costs, review the complete cost structure rather than focusing on one number. Pay particular attention to:- Monthly plan premium
- Medicare Part B premium
- Doctor visit copayments
- Specialist copayments
- Hospital costs
- Prescription drug costs
- Out-of-network cost-sharing
- Annual maximum out-of-pocket limit